Transaction Classification Workflow That Reconciles
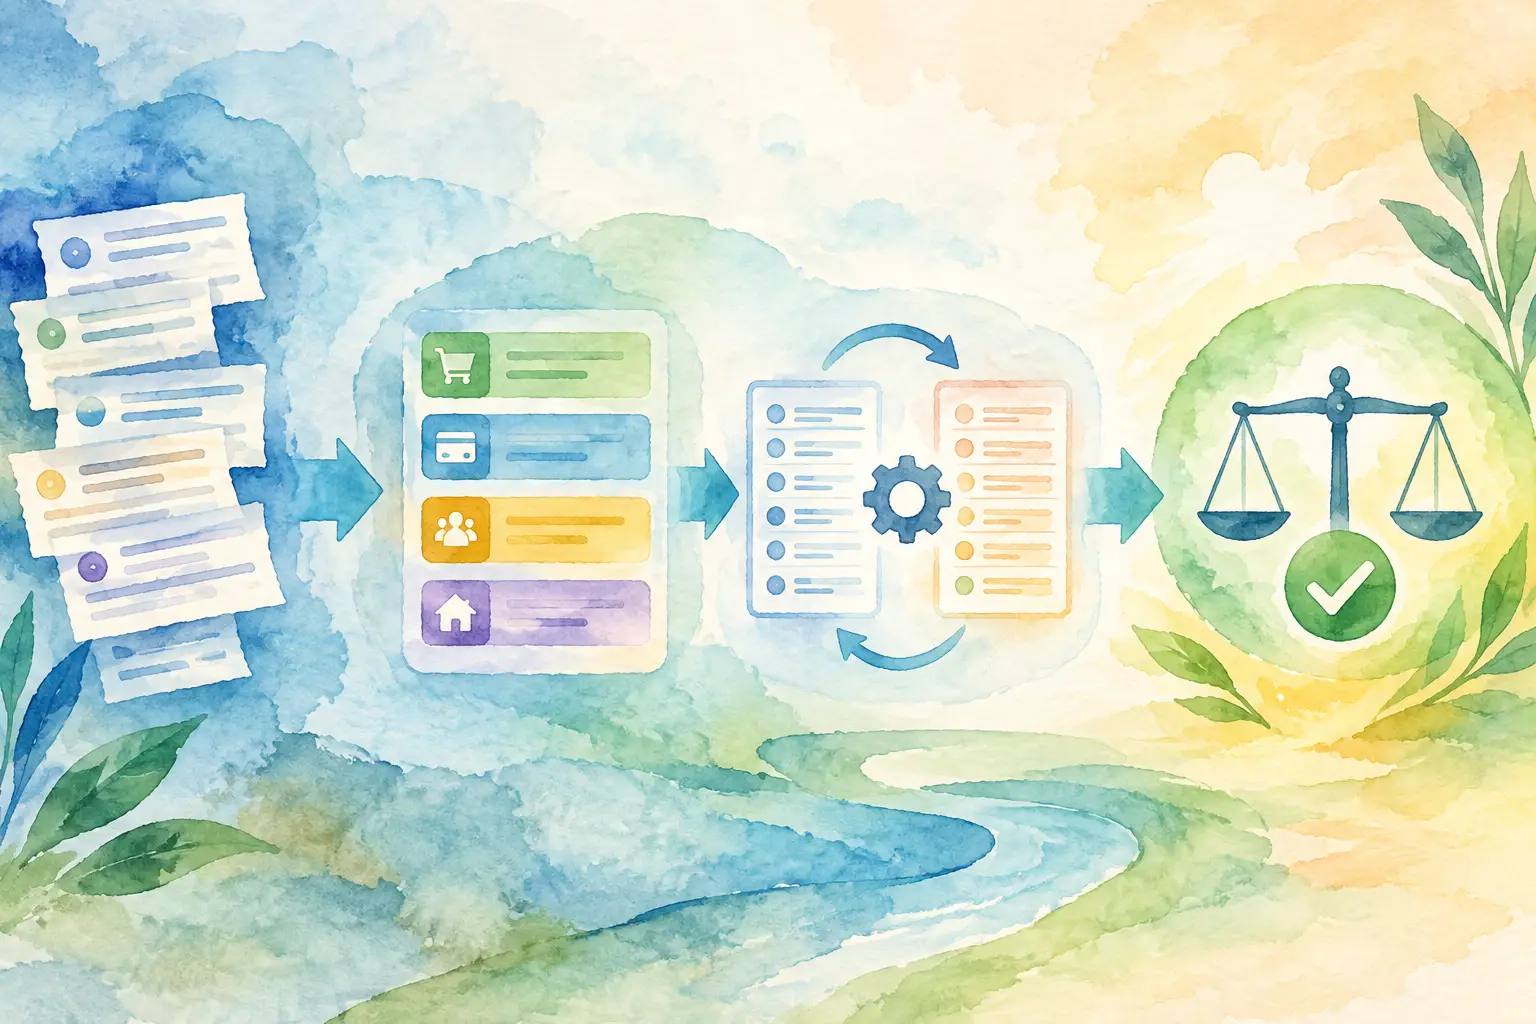
A transaction classification workflow is not a tagging exercise. It is the control layer between raw bank activity and financial statements a controller, operator, or CFO can trust. If a processor deposit is classified as revenue before its fees, refunds, and timing are understood, the income statement may look plausible while cash reporting, accounts receivable, and reconciliation are wrong.
The standard is higher than a clean-looking category list. Every transaction needs a source, a deterministic classification decision, supporting evidence, and a path to reconciliation. When the rules are replayable, the same source data produces the same ledger result. When a rule changes, the resulting change is visible, attributable, and reviewable.
What a controlled workflow must produce
A useful workflow begins with a clear output: a continuously reconciled general ledger that can serve the income statement, balance sheet, direct-method cash-flow statement, and cash forecast. Classification is one stage in that system, not the system itself.
For each financial event, the workflow should preserve the original row and connect it to a journal entry or an explicit exception. A bank line for payroll funding, for example, is not automatically payroll expense. It may settle a payroll liability recorded from a provider report. A card transaction labeled "Amazon" may be supplies, software, inventory, a reimbursable expense, or a personal charge awaiting review.
The distinction matters because classification answers several different questions at once: what happened economically, when cash moved, which account should carry the balance, and what evidence supports the conclusion. One merchant label cannot answer all four.
| Workflow stage | Required result | Control objective | | --- | --- | --- | | Ingest | Immutable source row with account, date, amount, and source ID | Preserve provenance | | Normalize | Standard fields for merchant, counterparty, currency, and transaction type | Make rules consistent across feeds | | Classify | Account mapping, dimensions, and journal treatment | Apply accounting policy deterministically | | Reconcile | Source balances and ledger balances agree to $0.00 | Prove completeness and accuracy | | Review | Exceptions are resolved with evidence and an audit trail | Prevent silent assumptions |
Start with source integrity, not categories
A classification engine cannot repair incomplete ingestion. Bank accounts, credit cards, payment processors, loan feeds, payroll reports, and raw exports each describe different parts of the financial system. They should be loaded with stable external identifiers, source timestamps, posting dates, account ownership, and the raw description preserved intact.
Duplicates are a common source of false certainty. A transaction may arrive through a bank feed and again in a manually uploaded CSV. A card purchase may be pending one day and posted the next. A processor payout may appear as one bank deposit while the processor report shows hundreds of customer payments, fees, chargebacks, and tax remittances. The workflow needs matching rules that identify whether rows are duplicates, related records, or separate events.
Normalization comes next. Create canonical fields without overwriting source evidence. Merchant names can be standardized, but the original descriptor stays available. Processor activity should be separated into gross sales, refunds, fees, reserve movements, and payouts where the underlying report provides that detail. This is how a $9,700 bank deposit becomes an explainable settlement rather than a revenue guess.
Build deterministic classification rules in the right order
Rules should be explicit, ordered, and versioned. Broad keyword matching belongs at the bottom of the hierarchy, not the top. A precise rule based on source account, transaction type, counterparty, amount pattern, and memo text should take precedence over a generic merchant rule.
Consider a recurring payment to a payroll provider. The classification may vary based on the event type: employee net pay reduces a payroll clearing liability, employer taxes reduce a tax liability and record expense where appropriate, and provider fees are operating expense. Treating all withdrawals as wages will distort both payroll expense and the balance sheet.
A practical rule hierarchy is usually:
- Source-specific accounting events, such as processor fees, loan principal, or payroll settlements.
- Exact counterparty and account combinations with an approved ledger mapping.
- Recurring patterns supported by prior reviewed transactions.
- Conditional rules using amount, timing, department, location, or customer context.
- Review queues for transactions that do not meet a sufficient confidence threshold.
The last category is a feature, not a failure. Some transactions cannot be classified safely from the bank row alone. Owner distributions, intercompany transfers, mixed-use purchases, customer deposits, and unusual vendor payments require context. A controlled workflow routes them to review rather than assigning a convenient expense account.
Versioning is equally important. If the team changes its treatment of a vendor from software expense to prepaid expense, the system should show the effective date, rule version, approving user, affected rows, and resulting journal changes. AI may assist with suggestions or exception triage, but it should not silently alter a live calculation. AI can never override the replay.
Classify the accounting event and the cash event separately
Cash timing and accounting recognition often diverge. This is where many workflows break down. A cash receipt may settle an invoice, create deferred revenue, repay a receivable, or represent a loan advance. A cash outflow may pay a current bill, fund prepaid insurance, reduce debt principal, or transfer money between accounts.
A sound workflow records the relationship between the cash row and its accounting event. For invoice collections, the cash movement reduces accounts receivable rather than creating new revenue. For loan payments, principal reduces the liability while interest flows through the income statement. For transfers, both sides are balance-sheet movements and should never become income or expense.
This separation also makes direct-method cash flow useful. Finance leaders can see actual customer receipts, payroll cash, vendor payments, taxes, debt service, and capital spending by day. That view is more operationally honest than deriving an estimated cash position from net income after the fact.
Reconciliation is the gate, not the final cleanup
Classification should not be considered complete when all rows have categories. It is complete when the source account balance, cleared activity, and ledger activity reconcile to $0.00 for the relevant period. Reconciliation catches missing transactions, duplicate imports, failed mappings, incorrect transfer pairs, and settlements that were recorded at the wrong gross or net amount.
Use control totals at multiple levels. The opening balance plus all imported activity should equal the closing balance for each bank and card account. Processor gross sales less refunds, fees, reserves, and payouts should tie to the processor statement. Accounts receivable and accounts payable should roll forward based on invoices, bills, payments, credits, and adjustments.
This discipline changes review behavior. Instead of asking whether a category seems reasonable, the reviewer can ask a more precise question: does this classification preserve the account roll-forward, agree with external evidence, and produce the intended financial statement treatment? Every number traces back to its rows.
Design exception handling for speed without weakening control
An exception queue should show the decision-maker what they need to resolve a row: raw source data, normalized counterparty, prior similar transactions, proposed treatment, linked documents, and the downstream accounts affected. A reviewer should not have to search across a bank portal, spreadsheet, accounting system, and inbox to explain one payment.
Prioritize exceptions by financial impact and reporting risk. A $12 subscription with no mapping matters, but an unexplained $48,000 processor payout, a new debt draw, or a payroll clearing imbalance deserves immediate attention. Set ownership and aging expectations so unresolved items do not accumulate into month-end surprises.
The workflow should also distinguish between a missing rule and a one-time decision. If a recurring vendor requires repeated manual classification, create a tested rule. If a transaction is genuinely exceptional, retain the decision and evidence without creating a broad rule that could misclassify future activity.
Make the workflow serve cash decisions
Once transaction data is classified and reconciled, it can support decisions beyond close. A CFO can model whether projected collections cover Friday payroll, isolate recurring vendor cash requirements, or test the effect of adding a hire before committing to it. Those projections remain credible only when their opening cash, historical patterns, payables, receivables, and debt schedules originate from reconciled records.
Shekl applies this discipline across the path from source ingestion through ledger replay, direct cash reporting, and scenario analysis. The objective is not to automate judgment away. It is to make every classification decision inspectable, repeatable, and usable in the next operating decision.
The practical test is simple: take any balance on the dashboard and follow it back to the source rows, the rule version, the journal treatment, and the reconciliation result. If that path is clear, finance can move faster without asking the business to trust a black box.